





In Brief: Improving expectations for trip spending, volume and revenue signal renewed momentum, while rising costs and geopolitical uncertainty continue to weigh on travel decisions, according to a new GBTA industry poll
-
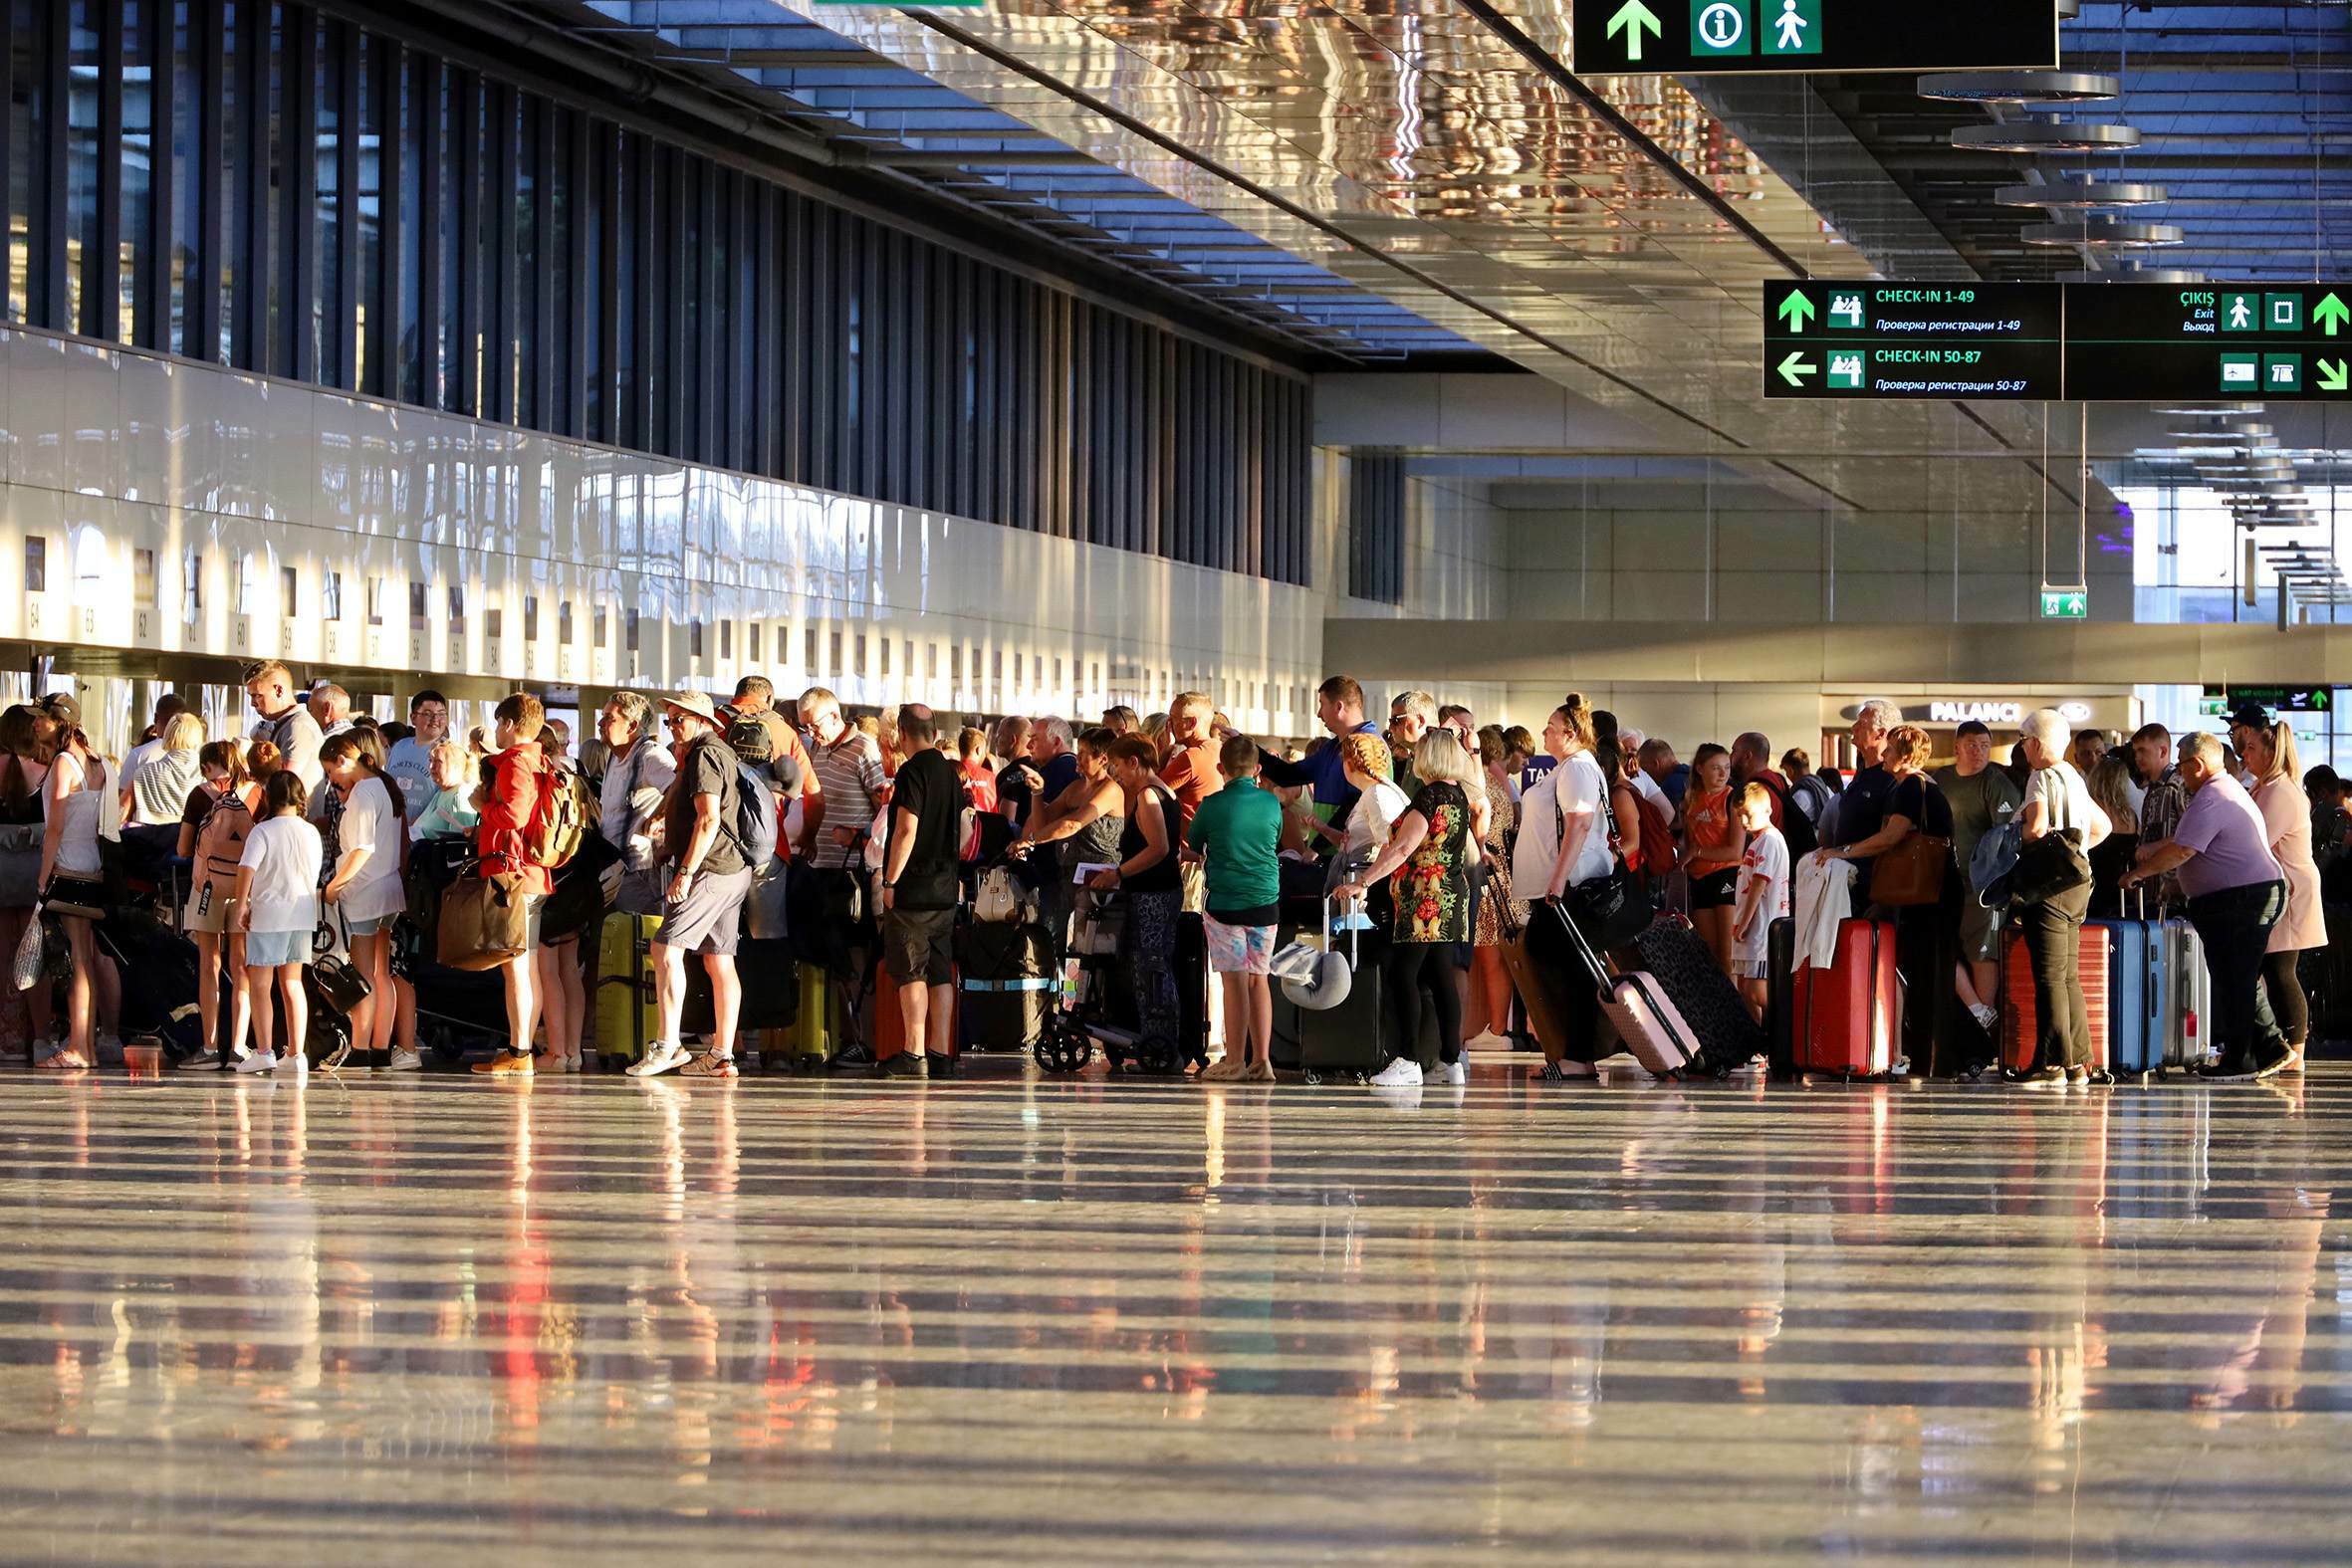
Business Travel Confidence Rebounds to Its Highest Level of 2026 As Industry Plans for Disciplined Growth – Image Credit GBTA
Business travel confidence has surged to its highest level of 2026, rebounding sharply from the uncertainty that weighed on sentiment earlier this year. Additionally, industry buyers and suppliers are increasingly optimistic about the next 12 months, with expectations for travel spending, trip volume and revenue all strengthening despite continued concerns about rising costs and geopolitical risk.
In the Global Business Travel Association’s (GBTA) latest poll of more than 600 business travel professionals worldwide, nearly two-thirds (63%) are optimistic about the industry outlook moving into 2027, up from 41% in GBTA’s April poll and above the 59% recorded in January. Pessimism fell from 24% in April to 7%. The sharp drop in confidence reflected in the April poll amid the Iran conflict and concerns over jet fuel prices has now reversed among buyers and suppliers and across every major region.
“Business travel continues to prove its resilience as well as its value as a catalyst for growth, collaboration and customer engagement,” said Suzanne Neufang, CEO of GBTA. “The rebound in sentiment we’re seeing across almost all regions is not simply about more travel, it’s about organizations becoming increasingly deliberate about where and why they travel. That combination of confidence, discipline and strategic investment bodes well for the industry’s continued momentum.”
Outlook and Optimism: 15 Months of Wide Swings
The latest GBTA poll results show sentiment has swung significantly over the past months. Optimism fell to 28% in June 2025, rose to 59% in January 2026, and dropped to 41% in April before climbing again in September.
- Nearly two-thirds of respondents overall (63%) are optimistic about the business travel industry over the next 12 months, up 22 percentage points from April.
- Only 7% are pessimistic, a big improvement over the 24% expressing pessimism in April.
- Corporate travel buyers and travel suppliers moved in step. Optimism rose from 39% to 61% among buyers, and from 42% to 64% among suppliers and travel management companies (TMCs).
- In terms of regions, Europe recorded the largest turnaround. In April, it was the only region where pessimism outweighed optimism, with 38% of Europe-based respondents pessimistic and 21% optimistic. In September, 55% are optimistic and 11% are pessimistic, a 61-percentage-point increase in net optimism, from -17 to +44. Still, optimism in Europe remains below the global average of 63%.
“Rising costs and geopolitical risk are now part of everyday planning for managed travel programs,” said Neufang. “Experienced business travel professionals are the people deciding which trips go ahead, keeping travelers safe and holding budgets steady when conditions shift. That expertise is what allows organizations’ confidence in travel and meetings to remain steady and grow.”
Spending, Volume and Revenue: Expectations Strengthen, With Spend Running Ahead of Trips
The rebound also extends beyond sentiment into business expectations for the remainder of 2026.
- Almost half of buyers (45%) expect the number of business trips taken at their organization to increase in 2026 compared with 2025, up from 30% in April. The share expecting a decrease fell from 28% to 16%.
- More than half of buyers (56%) expect their travel spend to increase, up from 43% in April. Europe-based buyers are the most likely to expect higher spend (65%).
- Nearly half (48%) of suppliers and TMCs expect their business travel-related revenue to increase, up from 35% in April and in line with the 47% recorded in January. The share expecting lower revenue fell from 27% in April to 14%, still above the 7% recorded in January.
- Among buyers, 31% expect the number of meetings their organization holds that require business travel to increase in 2026, while 49% expect no change and 14% expect a decrease.
Spend expectations continue to outpace volume expectations, which is consistent with continued pressure on travel costs.
Costs and Risk: Growth Moves Forward With Clear Guardrails
Buyers and suppliers face the same operating environment from different positions.
- Rising travel costs are the top influence on buyer travel planning, cited by 69% of buyers, followed by geopolitical uncertainty (45%), internal approvals and justification for travel (29%), traveler safety and security (25%) and airline or rail disruption (22%).
- Geopolitical uncertainty leads for suppliers and TMCs (60%), followed by rising operating costs (44%); customer pressure to reduce pricing, fees or costs (42%); changes in customer demand or travel volume (36%); and technology, distribution or AI challenges (29%).
Geopolitical concern is highest among Europe-based respondents, cited by 60% of buyers and 69% of suppliers and TMCs in the region. In North America, the figures are 35% and 53%. North American buyers put more weight on cost and process: 72% cite rising travel costs and 34% cite internal approvals and justification as challenges influencing business travel planning.
Destinations and Drivers: Home Markets Lead as Trips Tie Back to Growth
Buyers based in Asia Pacific, Europe and North America are generally most positive about travel within their own region.
- Nearly half of Europe-based buyers (47%) expect their organization’s travel within Europe to increase over the next 12 months, and 43% of North American buyers expect more travel within North America.
The Middle East has the weakest outlook of any destination region.
- About a third of buyers (34%) expect their organization’s travel to the Middle East to decrease over the next 12 months, compared with 14% who expect an increase.
- Among suppliers and TMCs, 40% expect customer demand for Middle East travel to fall.
Among buyers expecting more travel to a given region, business growth and market expansion are the leading drivers in Asia Pacific, Europe, and Latin America.
- North America is the exception, with customer, client and partner meetings (58%) and internal meetings and team collaboration (57%) ranking slightly ahead of business growth (53%).
- In Europe, business growth (60%), customer meetings (57%) and internal collaboration (47%) all rank highly.
Methodology
The GBTA poll was conducted online from August 27 to September 9, 2026, and drew responses from 604 GBTA members and non-members worldwide, including corporate travel managers, travel suppliers and intermediaries.
For more details and to access the full September 2026 GBTA poll results, visit the GBTA Research web page. For more information about GBTA Research, contact research@gbta.org.